The Future of Payments in Marketplaces: Cryptocurrency and Digital Wallets
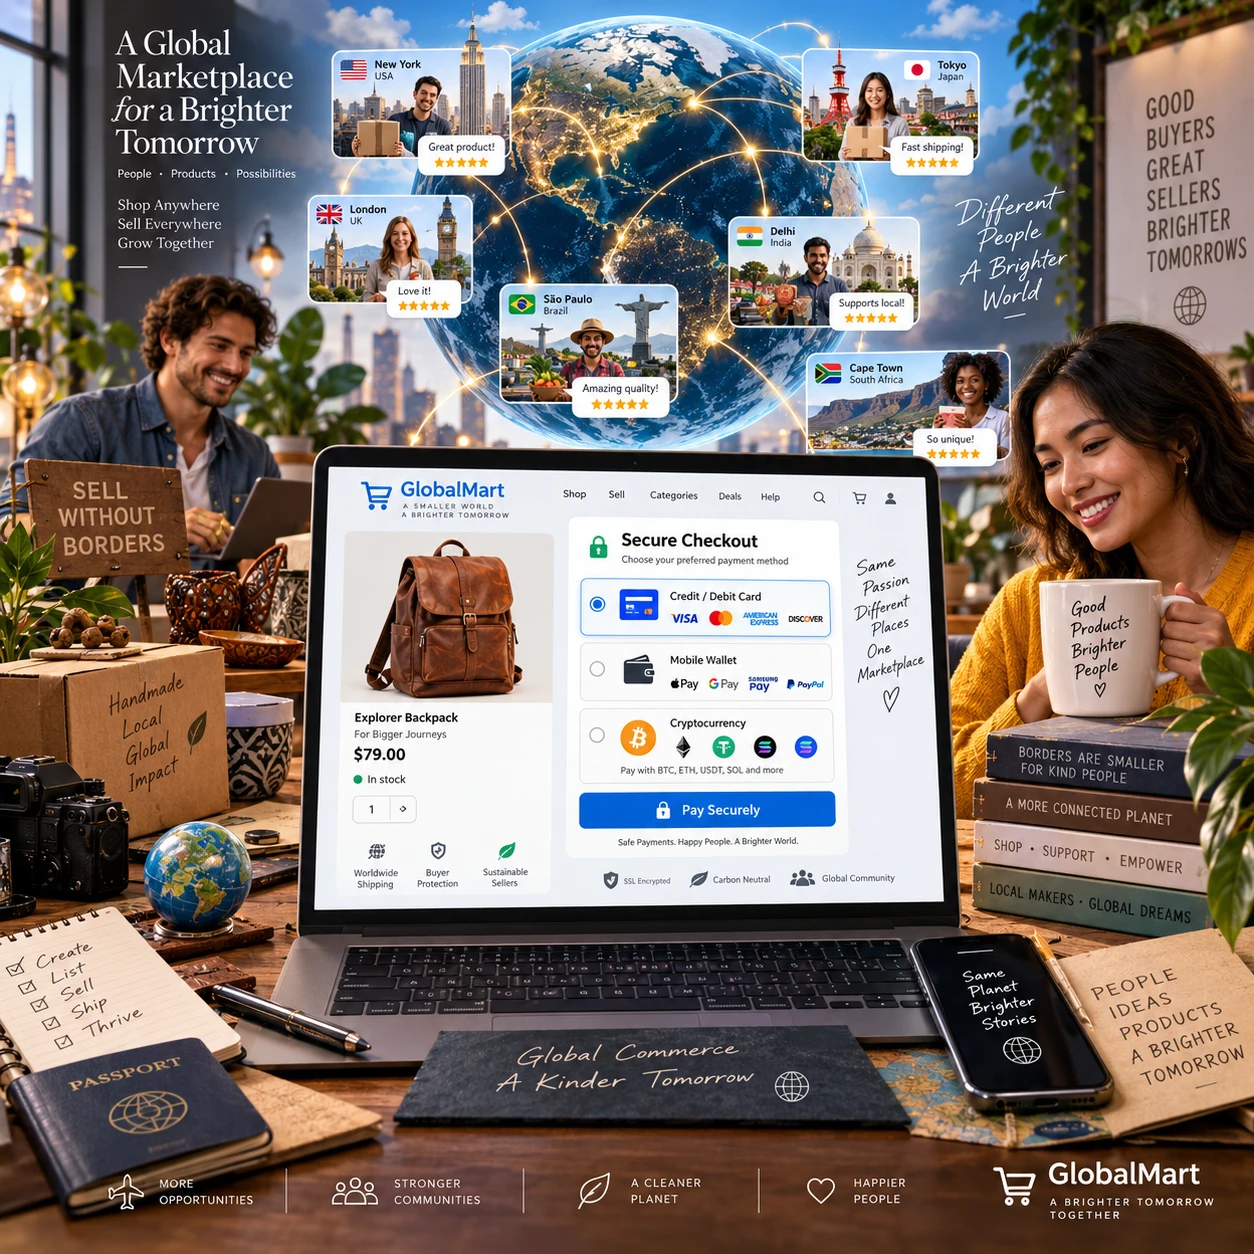
Payment options shape how easily buyers complete orders and how reliably sellers receive their earnings. In global online marketplaces, digital wallets and cryptocurrency are adding new possibilities alongside cards, bank transfers, and other established methods. Their role will depend on customer demand, local rules, payment infrastructure, and each marketplace’s appetite for operational risk.
How marketplace payments are evolving
Marketplace payments are evolving as buyers expect familiar, fast checkout choices and sellers need dependable access to funds across borders. Digital wallets are already part of everyday online commerce, while cryptocurrency remains a more specialized option whose suitability varies by market.
A marketplace payment is more than a checkout button. The platform may need to authorize and collect a buyer’s payment, manage disputes, calculate seller balances, handle refunds, and arrange payouts. A payment gateway or payment service provider can connect these steps to card networks, bank systems, digital wallets, or crypto payment processors.
Customers also differ by location and habit. One buyer may prefer a mobile wallet linked to a card; another may use a local payment app or bank transfer. Some customers may want to pay with cryptocurrency, but offering it does not automatically make checkout easier for the wider audience.
The practical direction is therefore more payment choice, managed market by market. Marketplaces are likely to combine established methods with selected newer options rather than replace conventional payments all at once. More choice can reduce checkout friction for some customers, but every additional method brings integration, support, fraud-prevention, and compliance work.
Digital wallets and cryptocurrency: What’s the difference?
Digital wallets store or access payment credentials for electronic transactions, while cryptocurrency is a digital asset recorded and transferred through a blockchain or related network. Some crypto wallets manage cryptocurrency, but most digital wallets used for shopping do not.
A conventional digital wallet, such as a phone-based wallet or online payment account, may hold tokenized card details or connect to a bank account. At checkout, the wallet generally asks the customer to authenticate the payment. The underlying transaction then moves through familiar card or bank infrastructure, subject to that provider’s terms and availability.
A cryptocurrency wallet manages the keys used to authorize transactions on a blockchain. The wallet may be self-custodied by the user or hosted by a third-party provider. A marketplace that accepts crypto may receive the asset directly, or use a payment processor that converts it into a local currency. Those arrangements affect who handles custody, conversion, refunds, and transaction monitoring.
Stablecoins are cryptocurrencies designed to track the value of an asset, often a national currency. They may reduce exposure to price swings compared with more volatile cryptocurrencies, but they still carry issuer, reserve, liquidity, network, and regulatory risks. A stablecoin is not identical to cash or a bank deposit.
- Digital wallet payment: often uses card or bank rails, with the wallet serving as a convenient interface.
- Crypto payment: transfers a digital asset on a blockchain or through a processor that supports crypto settlement.
- Stablecoin payment: uses a token designed to maintain a target value, with risks that depend on its design and provider.
Potential benefits for global marketplaces
Digital wallets and cryptocurrency may give global marketplaces more ways to serve customers and sellers, especially when local payment preferences or cross-border payment constraints matter. The gains depend on the countries, providers, currencies, and customer groups involved.
Digital wallets can shorten checkout by letting a buyer authenticate without repeatedly entering card details. That familiarity may help on mobile devices, though wallet availability and customer preferences differ by country. Supporting popular regional options can matter more than adding a payment method simply because it is new.
Crypto payments may appeal to some buyers who already hold digital assets, and blockchain-based transfers can operate across borders without using the same path as a conventional card payment. In some cases, a provider may offer settlement or conversion options that suit a marketplace’s needs. However, network fees, exchange rates, processing charges, and cash-out availability determine the real cost. Crypto is not automatically cheaper or faster.
For sellers, a wider range of payout methods may improve access to earnings, particularly when they operate in countries with limited banking options. Yet marketplaces must verify that payout partners can legally serve each seller location and provide clear records for accounting and tax reporting. A payment option that expands reach can also increase support demands and reconciliation complexity.
The useful question is not whether a method is globally available in theory. It is whether it reliably serves a defined buyer or seller group at an acceptable total cost. Compare checkout completion, failed payments, refund handling, settlement time, transaction fees, and support contacts in a controlled pilot before expanding availability.
Challenges marketplaces need to weigh
Marketplaces adopting digital wallets or cryptocurrency must weigh usability and reach against cost, security, operational complexity, and regulatory compliance. The risks vary by payment method and jurisdiction, so no single control makes every option safe or suitable.
Volatility and conversion: Cryptocurrency prices can move between checkout and settlement. A payment processor that converts crypto into a local currency may reduce a marketplace’s exposure to price changes, but adds provider dependence, conversion costs, and settlement terms to review. Stablecoins reduce some price volatility by design, not every form of risk.
Fees and settlement: Transaction costs can include gateway charges, card or wallet fees, blockchain network fees, foreign-exchange spreads, and withdrawal costs. Compare the complete route from buyer payment to seller payout; a low fee at checkout may be offset later. Blockchain transactions may also be difficult or impossible to reverse, which changes how refunds and disputes work.
Security and fraud prevention: Wallet authentication can help protect account access, but it does not prevent every stolen-account or social-engineering incident. Crypto transfers sent to the wrong address may be hard to recover. Marketplaces still need identity checks where required, transaction monitoring, account protection, clear dispute procedures, and controls against suspicious seller or buyer behavior.
Regulatory compliance: Rules for crypto services, money transmission, consumer protection, sanctions screening, tax reporting, and data handling differ by country and can change. The Financial Action Task Force’s guidance on virtual assets provides an international reference point, but local laws and licensing requirements determine what a marketplace and its providers may do. Seek qualified legal and compliance advice before launch.
A frequent mistake is treating a payment processor as a complete compliance solution. Providers can supply tools and services, but the marketplace remains responsible for understanding its own obligations and contracts. Another is advertising “instant” or “low-cost” payments without testing actual settlement times and fees across target corridors.
What adoption could look like for buyers and sellers
Adoption works best when payment choices fit the full order lifecycle: checkout, settlement, seller payouts, refunds, and disputes. A marketplace should explain what each method does before a customer selects it and keep the experience consistent after payment.
At checkout, show the payment amount, currency, and any relevant conversion or processing terms before confirmation. For a crypto payment, state which asset and network are accepted, how long the quote remains valid, and what happens if the customer sends the wrong amount or uses an unsupported network. Avoid implying that a blockchain transfer can be reversed like a card payment.
For seller payouts, communicate the schedule, available currencies, fees, minimum thresholds, and identity-verification requirements. Sellers should know whether they will receive local currency, a stablecoin, or another asset, and who bears conversion costs. A payout method can be convenient for one seller and impractical for another if they cannot readily use or withdraw the funds.
Refund policy needs particular care. If the marketplace refunds a crypto purchase in local currency, the amount may differ from the original asset’s value at the time of payment. If it refunds in crypto, the marketplace must define the exchange rate, network, timing, and responsibility for transaction fees. Put the rule in plain language before purchase, not only in a long policy page.
Run a limited pilot before offering a new method across the platform. Track payment completion, failed or delayed transactions, total cost, refund resolution time, fraud losses, and support volume. Include buyers and sellers from the target markets in usability tests; successful technical integration alone does not prove that the payment flow makes sense to them.
Choosing a payment strategy for the future
Choose payment methods by testing four factors: customer demand, market fit, operational readiness, and risk tolerance. This framework helps a marketplace decide whether to expand conventional digital wallets, pilot crypto payments, or wait for stronger evidence.
- Customer demand: Identify which buyers and sellers ask for a method, and whether they can already complete transactions with existing options. Separate measurable demand from general interest.
- Market fit: Check local availability, currency needs, provider coverage, consumer expectations, and applicable rules in each target country. A method that works in one market may not be viable in another.
- Operational readiness: Map gateway integration, settlement, seller onboarding, reconciliation, refunds, customer service, fraud prevention, and reporting. Confirm who handles each task and what happens when a provider or network is unavailable.
- Risk tolerance: Decide how much exposure the marketplace can accept to volatility, irreversible transfers, third-party providers, regulatory change, and potential fraud. Set thresholds and review them after launch.
Start with the simplest option that solves a documented problem. If buyers abandon checkout because a widely used local wallet is missing, testing that wallet may offer a clearer case than adding cryptocurrency. If a defined cross-border seller group faces payout barriers, assess suitable payout providers and legal requirements before deciding whether blockchain settlement is relevant.
Use a payment partner only after reviewing its fees, supported countries, custody model, security controls, data practices, refund process, and exit terms. Keep the checkout modular where practical, so the marketplace can add or remove providers without redesigning its entire payment system. The future of marketplace payments will be shaped by customer needs and reliable execution, not by novelty alone.
Frequently asked questions
How do digital wallets differ from cryptocurrency wallets?
A digital wallet commonly stores or accesses card and bank credentials for online payments. A cryptocurrency wallet manages the keys used to send or receive digital assets on a blockchain. Some apps support both, but the payment systems and risks are different.
Can customers use cryptocurrency to pay in an online marketplace?
Yes, if the marketplace and its payment provider support the relevant asset and network in the buyer’s location. The marketplace should explain exchange rates, fees, settlement timing, and refund rules before accepting payment.
What payment risks should marketplaces consider?
Key risks include fraud, account takeover, provider outages, unexpected fees, delayed settlement, data exposure, and disputes. Crypto payments add considerations such as price volatility, wallet mistakes, network congestion, and transfers that may be difficult to reverse.
Are cryptocurrency payment rules the same in every country?
No. Countries can apply different licensing, anti-money-laundering, sanctions, consumer-protection, tax, and reporting rules to crypto-related payments. Marketplaces should assess each jurisdiction with qualified local legal and compliance advisers before launch.